Why it matters
The timing of performance and the timing of payment answer different questions. This is why cash and profit can tell different stories.
A worked example
A completed £1,000 service earns revenue in March and creates a receivable. April payment increases cash and clears that receivable; it is not a second sale.
Illustrative example · simplified assumptionsA common mistake
Counting an invoice and its later payment as two sales.
Where the idea needs care
This simplified example assumes the revenue recognition conditions are satisfied.
Apply the idea
Explain this concept using a different example from your spending, work, business or a policy debate. State what stays fixed and what could change the result.
See the supporting infographic
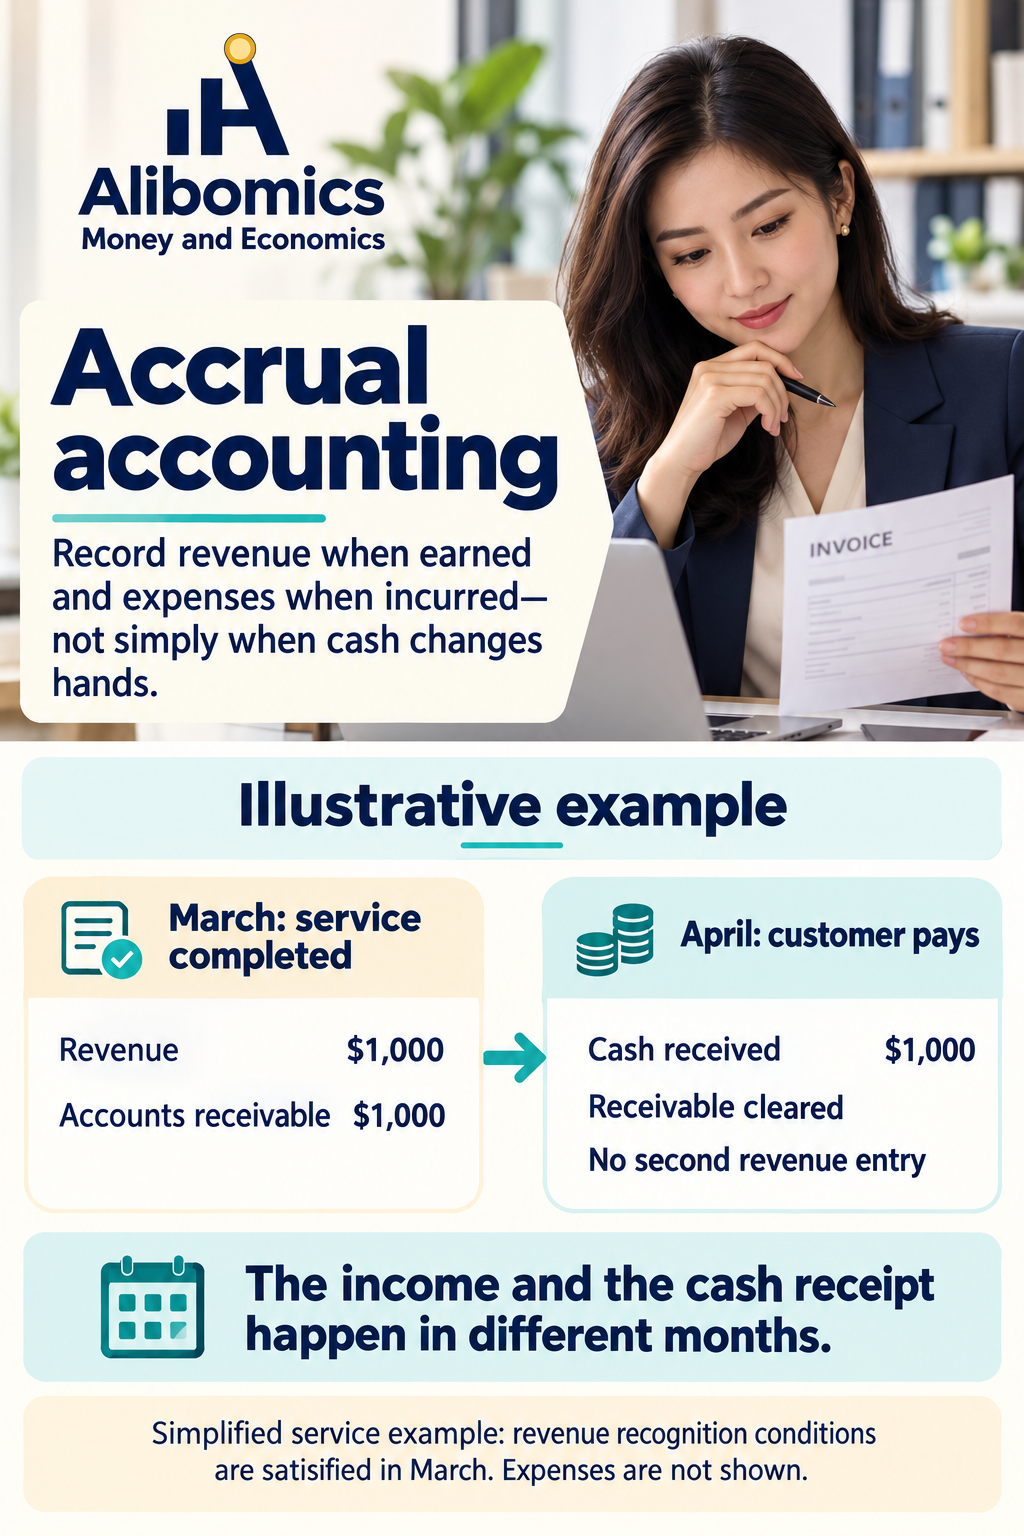
The written explanation above is the main lesson. This image offers another way to remember it.
Sources and further study
Examples and explanations by Alibomics. Numeric illustrations are not current market quotations.