Why it matters
An extra action should be evaluated using the benefits and costs it changes. This prevents a good next step being rejected because of costs already committed.
A worked example
One extra bakery batch would bring £80 of revenue and add £55 of avoidable costs. Its contribution is £25, before any other incremental effects.
Illustrative example · simplified assumptionsA common mistake
Using average historic costs instead of costs that change.
Where the idea needs care
Capacity limits, quality and future effects may change the additional cost or benefit.
Apply the idea
Explain this concept using a different example from your spending, work, business or a policy debate. State what stays fixed and what could change the result.
See the supporting infographic
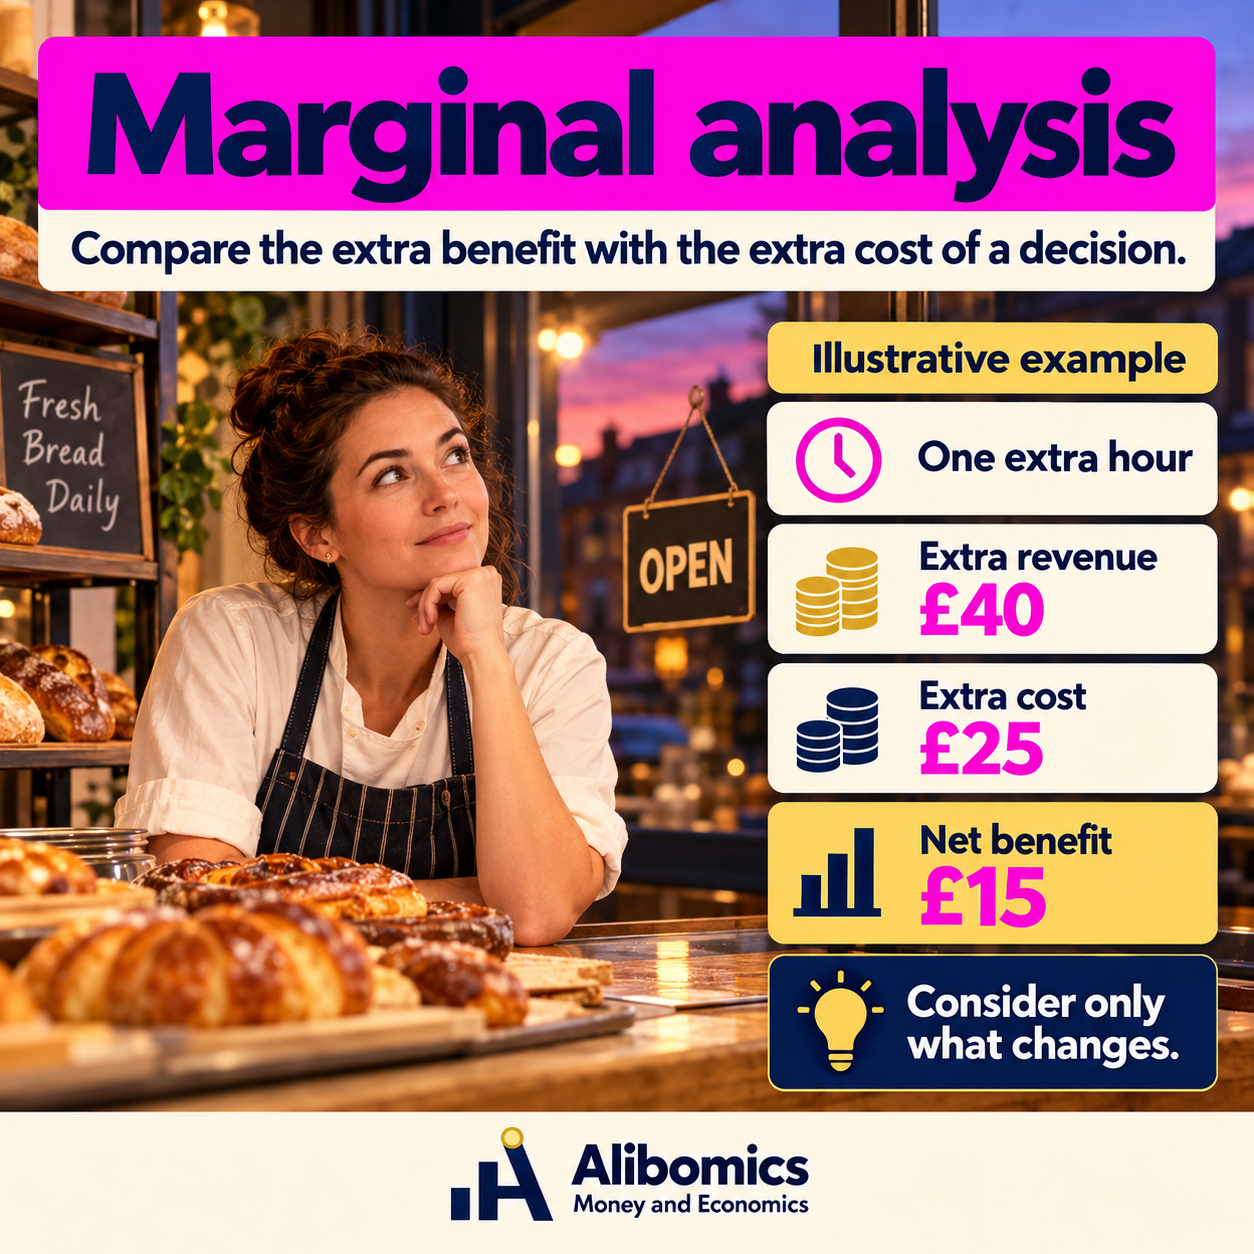
The written explanation above is the main lesson. This image offers another way to remember it.
Sources and further study
Examples and explanations by Alibomics. Numeric illustrations are not current market quotations.